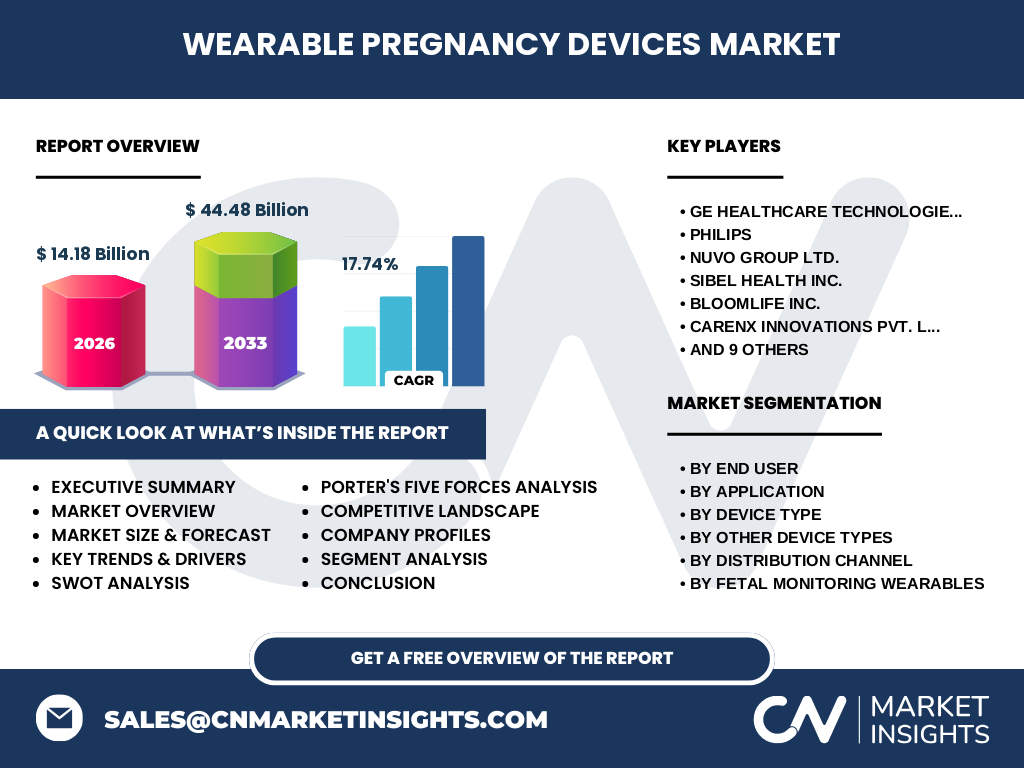
Market overview of the Wearable Pregnancy Devices Market
Our analysis indicates that the Wearable Pregnancy Devices Market is valued at 14.18 Billion in 2026. This specialized sector encompasses advanced medical-grade sensors, wireless telemetry patches, and smart textiles designed for continuous tracking of maternal and fetal biometrics outside traditional clinical environments.
What are the primary growth drivers and market restraints?
Structural growth is propelled by rising maternal ages and a surge in high-risk pregnancies, while stringent FDA and CE-mark clearance timelines act as notable regulatory constraints. Companies like Nuvo Group Ltd. and Bloomlife Inc. navigate these hurdles by securing targeted medical device approvals.
Emerging trends shaping the Wearable Pregnancy Devices Market industry trends
The shift toward decentralized healthcare has accelerated the adoption of multi-parameter pregnancy monitoring devices and remote telehealth integrations. Industry innovators are increasingly combining fetal heart rate monitoring wearables with AI-driven predictive analytics for early detection of pre-eclampsia.
How did the COVID-19 pandemic impact market trajectory?
The pandemic served as a major catalyst for the Wearable Pregnancy Devices Market, forcing a rapid transition toward virtual obstetric care and minimizing non-essential clinic visits. Remote patient monitoring platforms saw unprecedented uptake as hospitals sought to decompress overburdened maternity wards safely.
Competitive benchmarking and strategic dynamics
The competitive landscape features a blend of diversified medical giants like GE HealthCare Technologies Inc. and specialized agile startups such as HeraMED Limited. Market concentration is moderately high, with heavy investments directed toward proprietary sensor hardware and secure cloud data ecosystems.
Executive summary of the Wearable Pregnancy Devices Market research overview
Driven by expanding telehealth infrastructure, the Wearable Pregnancy Devices Market is poised for explosive expansion, scaling from 14.18 Billion in 2026 to 44.48 Billion by 2033 at a robust 17.74% CAGR.
Market forecast trajectory from 2027 to 2033
Our forecasting models project sustained double-digit expansion, achieving a market valuation of 44.48 Billion by 2033. This trajectory underscores a compound annual growth rate of 17.74%, fueled by consumer demand for proactive health tracking.
Segmentation analysis across application and device types
The market is segmented by device type into fetal, maternal vital sign, and uterine activity monitors, alongside applications covering High Risk Pregnancy Management and Remote Patient Monitoring. Hospitals and home care settings represent critical deployment vectors for these distinct categories.
Geographic distribution and regional performance
Regional performance varies significantly, with North America leading adoption due to advanced reimbursement frameworks, followed by Europe's stringent regulatory ecosystems. Meanwhile, Asia-Pacific presents untapped potential driven by expanding digital health initiatives in emerging economies.
In-depth regional review of high-growth territories
North America dominates the Wearable Pregnancy Devices Market, supported by high penetration of connected medical tech and proactive venture investments in maternal health startups. Asia-Pacific is emerging as the fastest-growing region, driven by localized manufacturing in countries like India through firms like CareNX Innovations Pvt. Ltd.
Company profiles and strategic positioning of key market participants
Industry leaders leverage distinct strategic advantages: Philips and Apple Inc. integrate consumer health ecosystems with clinical-grade accuracy, whereas specialized players like Janitri Innovations Private Limited focus on cost-effective, portable solutions for resource-constrained clinical settings.
Porter's Five Forces analysis of competitive intensity
Industry rivalry is intense, driven by rapid technological obsolescence and frequent new product launches from firms like Fitbit LLC and Bellabeat Inc. Buyer power remains moderate due to product differentiation, while supplier power over specialized biocompatible raw materials is relatively high.
SWOT analysis of the Wearable Pregnancy Devices Market
Key strengths include continuous remote data capture and early complication detection; weaknesses involve skin irritation from adhesive patches and high initial hardware costs. Opportunities lie in emerging market expansion, while strict data privacy regulations pose ongoing compliance threats.
Value chain analysis from raw materials to end-users
The value chain initiates with advanced semiconductor and biocompatible silicone sourcing, flowing through precision OEM manufacturing by companies such as Shenzhen Hwatime Biological Medical Electronics Co. Ltd., and culminating in delivery via e-commerce and hospital distribution channels.
Investment insights and high-potential strategic areas
Venture capital and strategic acquirers should prioritize platforms integrating multi-sensor pregnancy monitoring with AI-driven clinical decision support. Companies focusing on seamless electronic health record interoperability command superior valuations and long-term defensibility.
Conclusion and core takeaways for stakeholders
The Wearable Pregnancy Devices Market represents a high-growth paradigm shift in modern obstetrics. Reaching 44.48 Billion by 2033 at a 17.74% CAGR, success depends on navigating regulatory hurdles while delivering clinically validated, patient-centric remote solutions.
Research methodology powering our baseline estimates
Our baseline figures are triangulated using a rigorous blend of primary stakeholder interviews with obstetricians, secondary data from national health registries, and macroeconomic indicators concerning digital health adoption rates to ensure absolute market accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics for the Wearable Pregnancy Devices Market from 2026 to 2033, analyzing device types, distribution channels, and end-user segments while explicitly excluding non-connected, traditional analog obstetric diagnostic hardware.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic distribution partnerships and FDA clearances secured by innovators like Sibel Health Inc. and Kali Healthcare Pty Ltd, expanding remote monitoring capabilities globally and validating clinical efficacy for home-based maternal care.